DRAFT PREVIEW: pending the agent's approval. Not for distribution.
Back to the main website

Free Financial Checkup

A clearer financial picture begins with a focused conversation.

Set aside 30 minutes on Zoom to organize your priorities, review what matters now and identify practical next steps.

Start with the questions that matter to you.

This checkup is a focused conversation about what you understand today and where you want more clarity.

  1. 01
    Choose a weekday timePick any half-hour start between 9:00 AM and 8:00 PM Eastern.
  2. 02
    Complete the short formShare your name and mobile number together with your requested appointment time.
  3. 03
    Watch for a confirmation callWildert will call for a quick confirmation before your Zoom meeting.
Choose your requested time

When would you like to meet?

Choose a weekday start time and enter your contact details. Your requested time appears below before you send your request.

Your requested 30-minute Zoom meeting

Your name and mobile number are used only to arrange and follow up on your free financial checkup.

What happens next: Wildert will call for a quick confirmation before the Zoom.

Your booking request is in.

Your requested 30-minute Zoom meeting

What happens next: Wildert will call for a quick confirmation before the Zoom.

Financial education for stronger families

Clarity today.Confidence for tomorrow.

Destiny Group helps families understand the financial decisions that shape protection, taxes, probate, legacy and long-term wealth.

Not sure where your family stands? Answer 10 direct questions, in about two minutes, and see exactly where you stand.

Take the Protection Questionnaire
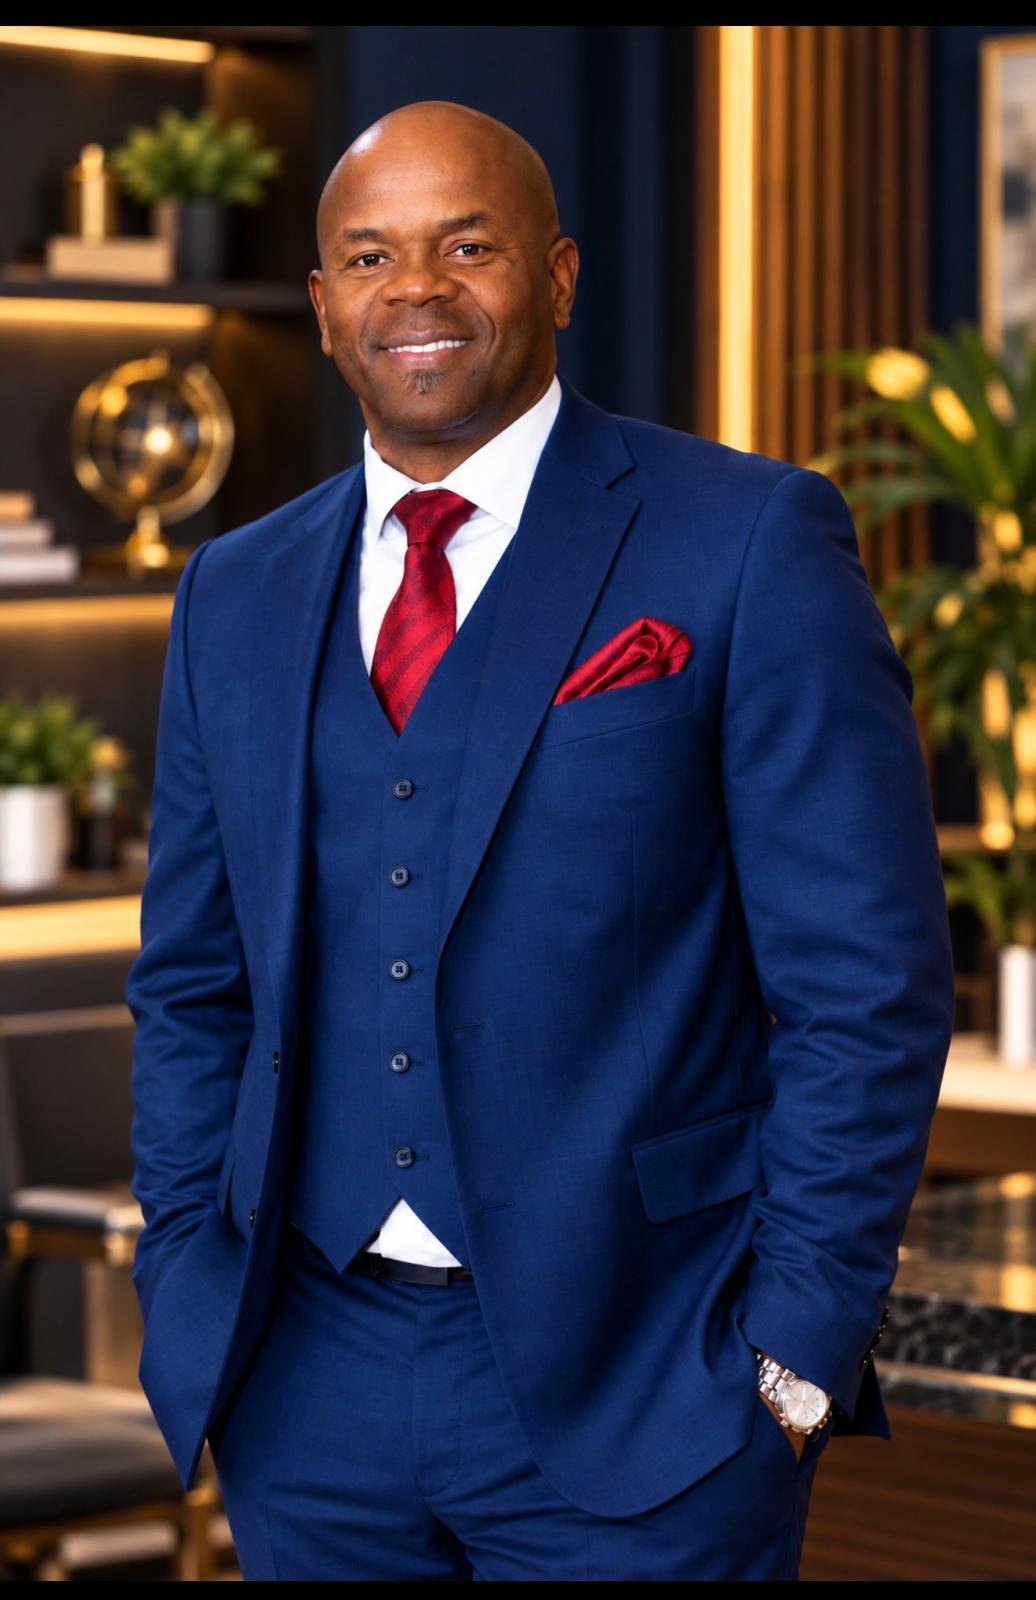
Wildert Charles, Licensed Insurance Producer
Wildert CharlesLicensed Insurance Producer

Create Your
Own Destiny.

Families deserve the knowledge to make thoughtful decisions, protect what matters and approach the future with purpose.

Portrait of Wildert Charles

About Wildert Charles

Education grounded in clarity and care.

Wildert Charles offers financial education, protection and legacy: helping people protect themselves and their families, and leave a legacy for the people they love.

Wildert works with people who want to start protecting themselves early, with families, with entrepreneurs, and with people preparing for retirement, from Holbrook and across Massachusetts.

Meet Wildert Charles

Education. Protection. Legacy.The Destiny Group standard

Four pillars of financial understanding.

Each topic is presented as general education, giving families a sound foundation for more informed decisions and professional conversations.

01

Protection

Understand how income, obligations and family responsibilities fit into a broader protection conversation. Thoughtful planning starts with seeing the full picture.

02

Taxes

Learn how tax treatment can influence financial decisions over time. The goal is awareness of the questions worth bringing to a qualified tax professional.

03

Probate & Legacy

Explore how assets may transfer, why beneficiary details matter and where probate can affect a family. Clear records and professional guidance are essential.

04

Wealth & Compounding

See how consistency, time and long-term thinking shape financial progress. Education helps families recognize the value of starting early and staying intentional.

A family conversation

Legacy begins with what a family understands.

Good planning is easier when the people involved can discuss their intentions, organize important information and know which professionals to consult.

Read the conversation starters

Insights for a more informed household.

Full articles that bring probate, beneficiary paperwork and long-term planning into plain view before your next professional conversation.

Probate & legacy

What probate is, and who pays for the process

A plain-language look at estate administration, common steps and how related expenses can affect what remains for a family.

Beneficiary planning

When a will and beneficiary paperwork disagree

Why the instructions on certain accounts can matter as much as the words in a will, and what families can review now.

Long-term planning

What time does for money

How compounding, consistency and regular review can shape financial progress over a long horizon.

Probate & legacy

What probate is, and who pays for the process

Probate is a legal process used to settle a person’s estate after death. The exact rules differ by state, but the work often includes confirming a valid will, appointing someone to administer the estate, identifying property and debts, addressing valid claims and distributing what remains to the people or organizations entitled to receive it.

The person responsible for that work may be called an executor or personal representative. The title varies, but the responsibility is substantial. That person may need to gather records, secure property, communicate with institutions, file court documents, arrange appraisals, address tax filings and keep beneficiaries informed.

Where the costs come from

Estate administration can involve filing fees, professional help, property expenses, appraisals, accounting work and other costs. The amount depends on the estate, local rules, how organized the records are and whether disagreements arise.

Eligible administration expenses are commonly paid from estate assets before the remaining property is distributed. In practical terms, those expenses can reduce what is available to pass on. A family member may sometimes advance an expense and seek reimbursement, but the rules and required documentation depend on the situation.

A will is important, but it may not avoid probate

A will states who should receive probate property and who should administer the estate, subject to applicable law and court approval. It does not automatically keep every asset out of probate. How an asset is titled, whether it has a valid beneficiary designation and the laws of the state can all affect how it transfers.

That is why preparation is more than writing a document. A useful starting point is an organized record of important accounts, property, debts, professional contacts and the people expected to handle key responsibilities.

This article provides general education, not legal or tax advice. Probate rules and expenses vary. Bring legal questions to an estate-planning attorney licensed in your state, and tax questions to a qualified tax professional.

Start with a clearer picture.

A free financial checkup can help you organize the questions you want to bring to the right professionals.

Book a free financial checkup
Beneficiary planning

When a will and beneficiary paperwork disagree

A will can be central to an estate plan, but it does not necessarily control every asset. Many financial accounts and benefits allow the owner to name a beneficiary directly. When that valid designation applies, the account instructions generally govern that asset, even if the will says something different.

This distinction can surprise families. A will usually directs property that becomes part of the probate estate. An account with a valid beneficiary designation may transfer under the account agreement instead. Joint ownership, trusts and state law can add other layers, so the outcome depends on the asset and the facts.

How conflicts happen

Paperwork often falls out of step after a major life event. Marriage, divorce, a birth, a death or a changed family relationship may prompt someone to update a will while overlooking older account forms. A misspelled name, an incomplete designation or a beneficiary who died first can also create uncertainty.

Even when the documents are technically valid, inconsistent instructions can lead to confusion and conflict. The people left behind may be forced to work through a result that no longer reflects the account owner’s intentions.

A coordinated review matters

Start by making a list of the assets that allow beneficiary designations. Review the primary and contingent beneficiaries on each one, and compare those instructions with the broader estate plan. Confirm names, relationships and any information the institution requires. Then repeat the review after major life changes and at reasonable intervals.

Do not change legal or account documents based only on a general checklist. The interaction among beneficiary forms, a will, account ownership and state law can be complex. The goal is to identify questions and bring them to the professionals who can evaluate your circumstances.

This article provides general education, not legal or tax advice. Ask an estate-planning attorney how your documents work together under applicable law, and direct tax questions to a qualified tax professional.

Bring the paperwork into one conversation.

A free financial checkup can help you identify what to review and which questions need professional guidance.

Book a free financial checkup
Long-term planning

What time does for money

Time can change the role that each financial decision plays. A single contribution is one event. A consistent habit, repeated over many years, can become part of a much larger result. That is the basic idea behind compounding.

Compounding happens when growth is added to a balance and future growth can build on both the original amount and prior gains. It can be powerful over a long horizon, but it is not a promise. Results depend on returns, fees, taxes, withdrawals, inflation and the choices made along the way. Values can rise or fall.

Starting earlier changes the workload

More time can give repeated contributions and any growth more opportunities to accumulate. Starting early may also reduce the pressure to make up for lost years with larger contributions later. Starting later does not mean planning has no value; it means the plan should reflect the time that is actually available.

Consistency matters because long-term progress rarely depends on one perfect moment. A practical plan accounts for regular saving, changing income, unexpected expenses and the temptation to abandon a strategy when conditions feel uncertain.

Compounding needs a plan around it

A long horizon does not remove risk. Review costs, access to funds, tax treatment, time frame and the amount of fluctuation you can reasonably accept. Separate near-term needs from money intended for later goals so a short-term expense is less likely to disrupt a long-term decision.

Regular reviews keep the plan connected to real life. A new job, a growing family, a move or a change in priorities can all affect how much someone can set aside and when it may be needed. The value of time comes from giving thoughtful decisions room to work, then adjusting those decisions when the facts change.

This article provides general education, not financial, investment or tax advice, and no outcome is guaranteed. Discuss tax questions with a qualified tax professional and seek appropriately qualified guidance for decisions about your circumstances.

Give your long-term questions a starting point.

A free financial checkup can help you take stock of your priorities and prepare for a more focused planning conversation.

Book a free financial checkup

Questions families often ask.

Short starting points for conversations about protection, probate, taxes and long-term planning. Individual circumstances and state rules can change the answer.

What is probate?

Probate is a legal process that may be used to validate a will, appoint someone to administer an estate, address valid debts and distribute remaining property. The process and terminology vary by state, so an estate-planning attorney can explain how local rules may apply.

Does having a will mean my family avoids probate?

Not necessarily. A will generally provides instructions for property that enters the probate estate, while the way an asset is titled or designated may affect whether it goes through that process; an estate-planning attorney can review the specific documents and state law.

What is a beneficiary form?

It is a document or account instruction naming who should receive certain assets or benefits after the owner’s death. When valid and applicable, the designation may control that asset, which is why it should be reviewed alongside a will and the rest of the estate plan.

Who settles an estate?

A court may appoint an executor or personal representative to administer the estate, often based on the person named in a valid will. That individual’s duties and authority depend on state law and the estate, so legal guidance can be important.

Who pays probate and estate-administration expenses?

Eligible expenses are commonly paid from estate assets before distributions are made, which can reduce what remains for beneficiaries. Costs and payment rules vary, so ask an estate-planning attorney about legal expenses and a qualified tax professional about any tax consequences.

What does family protection planning include?

It can begin with understanding income, regular obligations, emergency resources and the people who depend on you. The goal is to see the full household picture and identify the questions that require appropriately qualified guidance.

How can taxes affect a financial or estate plan?

Tax treatment may influence what a family keeps, when an obligation arises and how different decisions interact. Because the result depends on current law and individual facts, direct tax questions to a qualified tax professional.

What does compounding mean?

Compounding describes growth building on an original amount and on prior gains over time. It can support long-term progress, but returns are not guaranteed and actual results are affected by factors such as losses, fees, taxes, inflation and withdrawals.

Is starting early more important than starting big?

More time can give consistent contributions and any growth more opportunity to accumulate, while starting later may require a different pace. The right approach depends on resources, time horizon, needs and risk, and no particular result is guaranteed.

How do I start planning?

Begin by listing your household priorities, income, obligations, important accounts, beneficiary instructions and the people who may need to act on your behalf. A free financial checkup can help organize the conversation, while legal questions belong with an estate-planning attorney and tax questions with a qualified tax professional.

Free Financial Checkup

Set aside 30 minutes for a clearer next step.

Choose a weekday time for a focused Zoom conversation about the financial questions you want to understand more clearly.

30 minutesMonday–Friday9:00 AM–8:00 PM ETZoom
Choose a time & book By booking, you agree that Wildert Charles may contact you by phone or text about your checkup.

What to expect

01
Pick your time

Select an available weekday appointment in the booking form.

02
Share your contact details

Submit your name and mobile number so Wildert can reach you.

03
Connect on Zoom

After you book, you’ll get a quick confirmation call, then your 30-minute meeting happens on Zoom.

Begin with a conversation

Bring your questions into focus.

Book a free financial checkup to discuss the topics you want to understand more clearly.

Privacy

The booking form collects your name and mobile number. This information is used only to arrange and follow up on your free financial checkup.

Your information is never sold or shared with third parties for marketing. To request deletion, contact Wildert Charles directly.

Stay connected

Follow Wildert

LinkedInInstagram